Conflict, Oil Revenue, and Localization Ambitions Reshape Armored Vehicle Demand Across the Middle East
Ongoing regional conflicts and defense localization goals are pushing Middle Eastern nations toward rapid armored vehicle investment.
Sustained regional instability, recovering oil revenues, and ambitious domestic defense-industrial programs are combining to make the Middle East one of the world’s most competitive markets for armored vehicles, according to a Defense News analysis of procurement trends across the Gulf and the broader region. The convergence of those three forces has drawn major Western and Russian defense contractors into intensifying competition for contracts that stretch across wheeled and tracked platforms alike.
The demand signal is not abstract. Conflicts in Yemen, Syria, Libya, and Iraq have placed real operational pressure on national inventories, accelerating replacement cycles and surfacing capability gaps that governments are now moving to close. That battlefield consumption is feeding procurement urgency in a way that peacetime planning cycles rarely produce. Analysts covering the Iran conflict and broader Gulf tensions have noted that ground-force modernization is now tracking alongside missile defense and air power investments as a regional priority.
Oil Revenue and Procurement Cycles
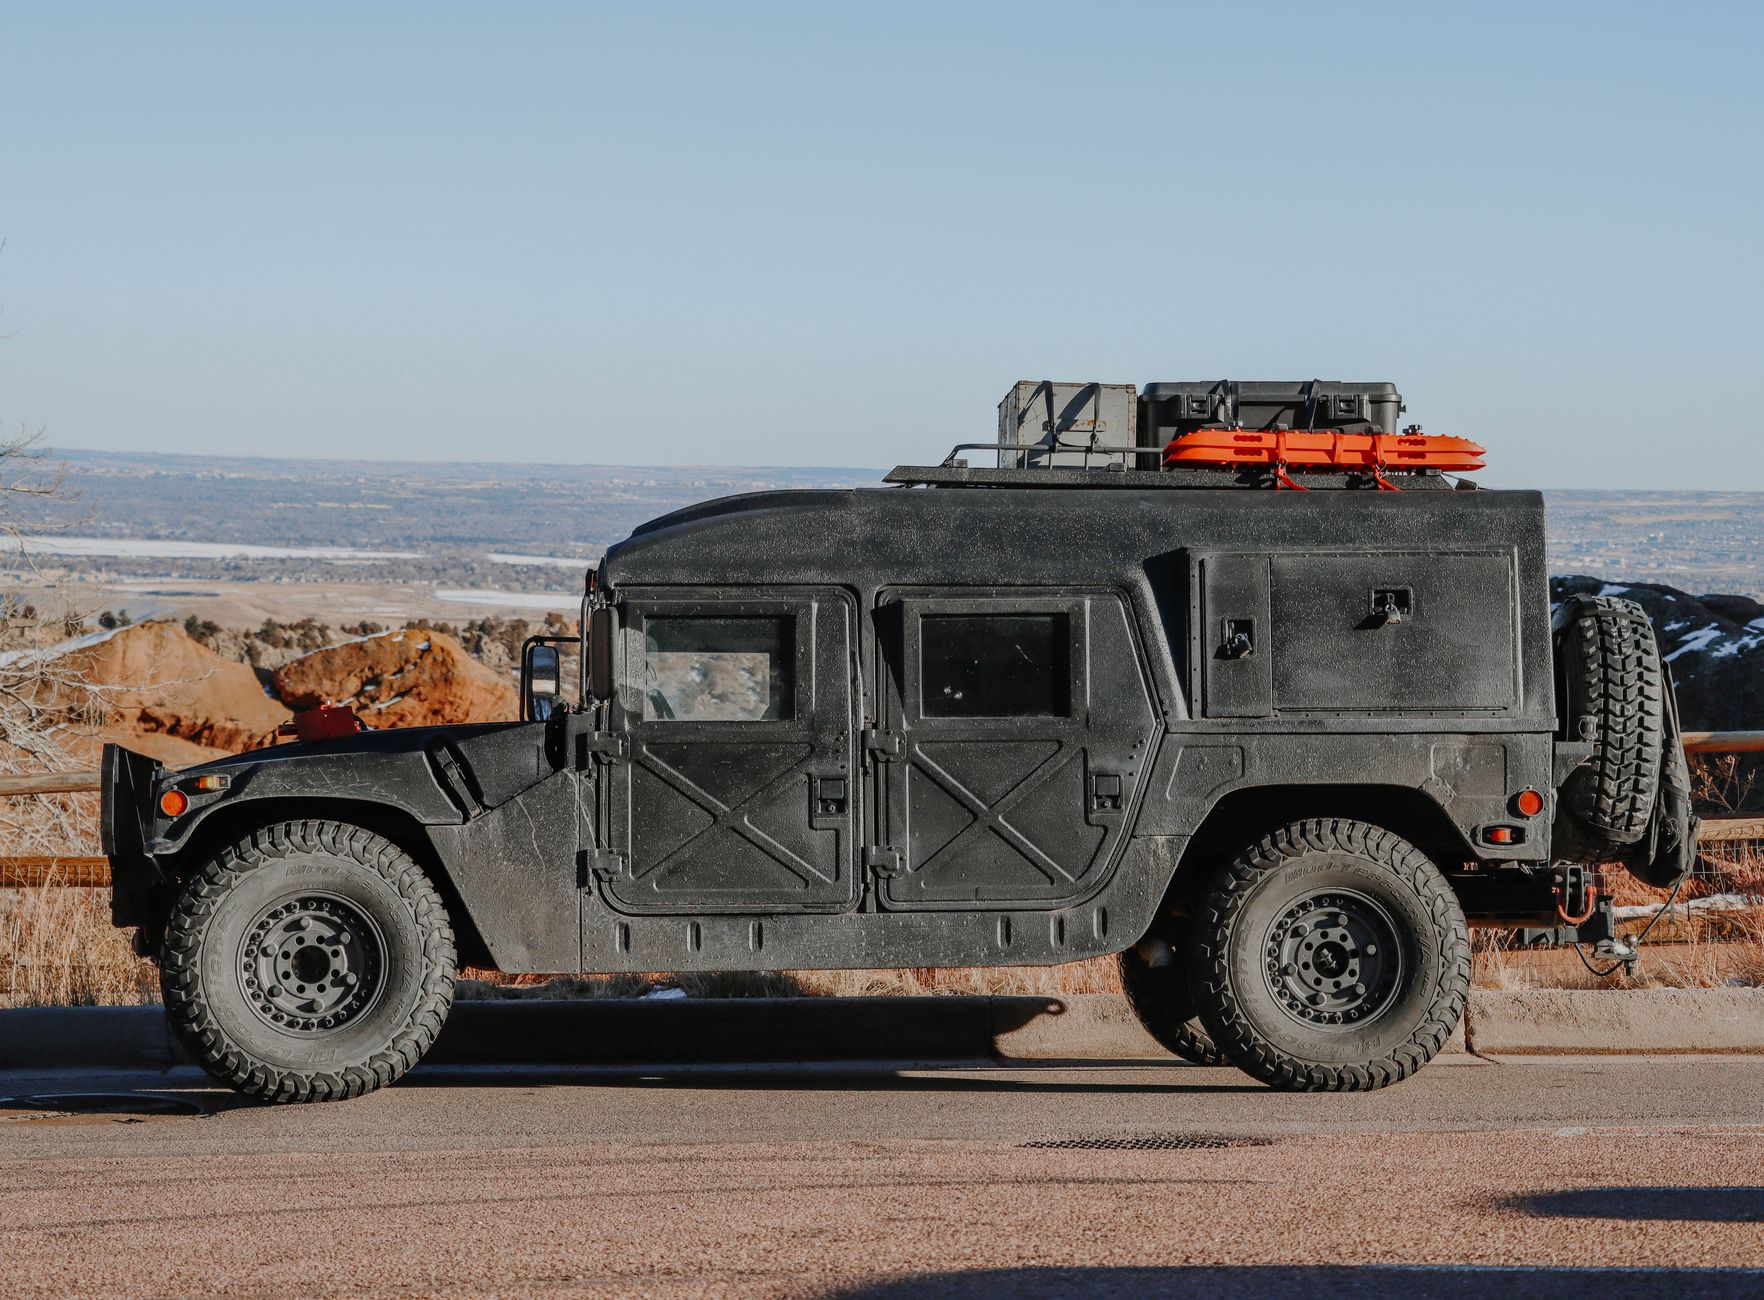
The fiscal backdrop matters considerably. Gulf states whose defense budgets contracted during the 2014–2016 oil price downturn have returned to more active procurement postures as energy revenues stabilized. Saudi Arabia, the United Arab Emirates, and Kuwait have all signaled intentions to expand or modernize ground vehicle fleets, with programs spanning light protected mobility platforms to heavier infantry fighting vehicles. The relationship between oil prices and Gulf defense spending has historically been direct, and current revenue levels are supporting multi-year contract commitments that require sustained budget confidence.
That spending, however, is not simply a function of available cash. Gulf governments are increasingly tying procurement decisions to offset and technology-transfer requirements, seeking to use large contracts as leverage to build domestic manufacturing capacity. Saudi Arabia’s Vision 2030 framework and the UAE’s efforts through its defense conglomerate EDGE are the most visible expressions of that strategy, but similar localization pressures are appearing in smaller regional states as well. Vendors that cannot offer meaningful in-country production arrangements are finding themselves at a structural disadvantage in competitive bids, regardless of platform performance.
Localization Mandates and Industrial Competition
The domestic content push is reshaping how international manufacturers approach the region. European, American, and Russian firms have each pursued joint ventures, licensed production agreements, and final-assembly arrangements in an effort to satisfy offset requirements while retaining proprietary system advantages. The Defense News reporting notes that this dynamic is intensifying competition rather than consolidating it, as no single supplier has achieved a dominant position across the Gulf’s varied requirements.
The variety of operational requirements across the region adds further complexity for vendors. Counterinsurgency experience in Yemen and Iraq has elevated demand for mine-resistant and ambush-protected configurations, while conventional deterrence planning in the Gulf drives interest in heavier tracked platforms capable of peer-level engagements. Few programs fit neatly into one category, and procurement offices in several countries are managing parallel acquisition tracks to satisfy both requirements simultaneously. That parallel demand is sustaining a broader market even when individual program timelines slip.
The competitive landscape also reflects the region’s willingness to diversify suppliers for strategic and political reasons. Countries that have historically sourced primarily from the United States or Western Europe have opened tenders to South Korean, Turkish, and Russian manufacturers, expanding the field and complicating alliance-management considerations for Washington and Brussels. Defense industry analysts expect that trend to persist so long as offset requirements and pricing differentials favor diversification over consolidation. For regional defense ministries, the leverage that comes from competitive sourcing is itself part of the procurement calculus, not an incidental byproduct of it.